Buying your first home is exciting, but it can also feel overwhelming. You may be wondering how much money you need, which neighborhoods fit your budget, how to qualify for a mortgage, and what happens after your offer is accepted.
If you are a first time home buyer in Charlotte, NC, understanding the process before you start touring homes can help you make better decisions and avoid costly surprises.
Charlotte offers a variety of housing options, from established neighborhoods with mature trees to newer communities with modern amenities. However, finding the right home involves more than choosing a property you like. You also need a realistic budget, suitable financing, a clear understanding of the local market, and a plan for the buying process.
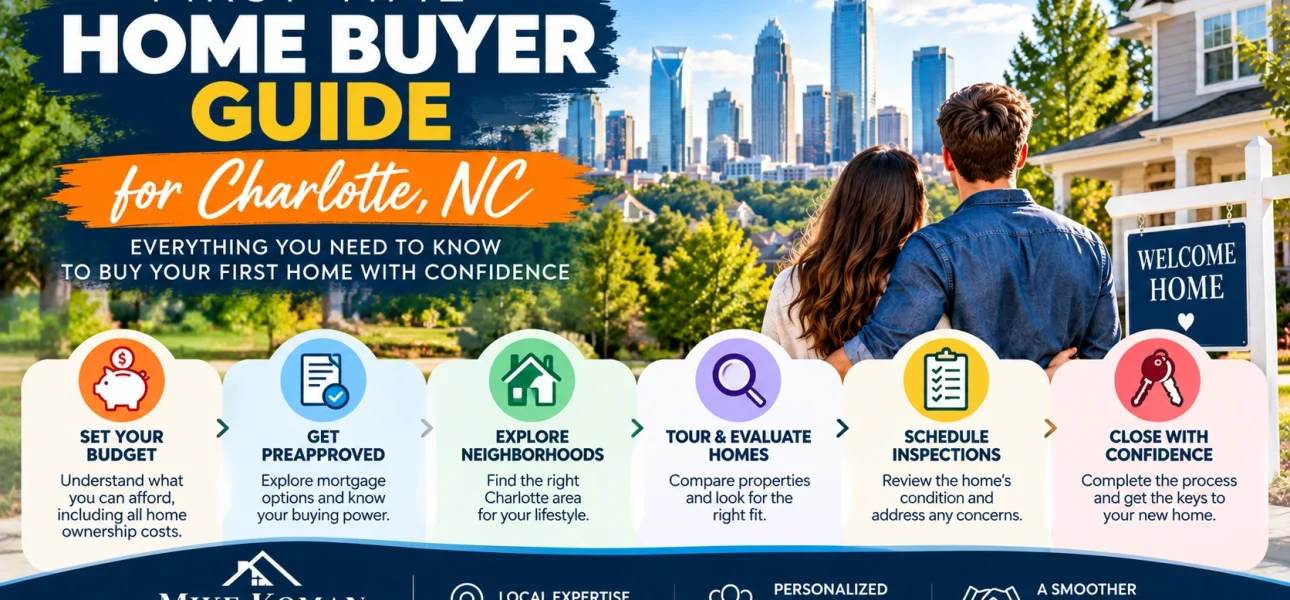
First-time home buyer guide for Charlotte: Step by Step
1. Understand the Charlotte, NC Housing Market
Before searching for homes, take time to understand the market and the types of properties available in your preferred area.
Charlotte has a diverse housing market. Buyers can find condominiums, townhomes, traditional single-family houses, and new construction communities. Prices and competition vary by neighborhood, property condition, home size, and proximity to major employment centers.
For example, a buyer who wants a larger home and a yard may find different options in the suburbs than in a neighborhood closer to Uptown Charlotte. A buyer who values a shorter commute may prefer a smaller property closer to work.
The market also changes over time. Redfin reported a median Charlotte home sale price of approximately $420,000 for the three months ending September 2026. This is a citywide reference point, not a prediction of what you will pay in a specific neighborhood. Prices can vary significantly by property type and location.
Before setting your budget, research recent comparable sales and homes currently available in your target areas.
What should first-time buyers look for in Charlotte?
Consider these factors when comparing neighborhoods:
- Commute: Estimate travel time to work, school, and other regular destinations.
- Affordability: Compare home prices with your total monthly housing budget.
- Daily convenience: Check access to grocery stores, healthcare, parks, and other services.
- Future needs: Think about whether the home will suit your plans over the next five to seven years.
- Property condition: Consider the age of the roof, HVAC system, plumbing, and other major components.
A home that looks affordable initially may become less attractive if it requires extensive repairs or adds significant commuting expenses.
2. Determine How Much Home You Can Afford
One of the biggest mistakes a first-time home buyer in Charlotte, NC can make is focusing only on the purchase price.
Your actual housing expense includes more than your mortgage payment. Depending on the property and loan, you may also pay property taxes, homeowners insurance, mortgage insurance, HOA dues, and ongoing maintenance costs.
Before browsing listings, calculate a monthly budget that accounts for all these expenses.
What costs should you include?
Your homeownership budget should consider:
- Mortgage principal and interest
- Property taxes
- Homeowners insurance
- Mortgage insurance, if applicable
- HOA or condominium fees
- Utilities and routine maintenance
- Savings for unexpected repairs
For example, imagine a buyer can comfortably spend $2,500 per month on housing. A lender might approve a loan that results in a higher monthly payment, but that does not automatically mean the buyer should spend that much.
The right budget leaves room for groceries, transportation, retirement contributions, emergencies, and other financial goals.
Practical tip: Use a mortgage calculator to estimate payments at different purchase prices. Then ask a lender to provide estimates that include taxes, insurance, and applicable mortgage insurance.
3. Check Your Credit and Get Mortgage Preapproval
Mortgage preapproval is an important early step when buying your first home in Charlotte. A lender reviews your financial information to estimate how much it may be willing to lend. The lender may examine your credit history, income, debts, employment, savings, and other financial details.
A preapproval letter can help you understand your purchasing range and demonstrate to sellers that you are a serious buyer. However, it is not a guaranteed loan offer. Final approval depends on further underwriting and the property itself.
How to prepare for mortgage preapproval
Before applying, gather documents such as:
- Recent pay stubs
- W-2 forms or tax returns, as requested
- Bank and investment account statements
- Information about existing debts
- Identification and employment details
Ask lenders about the interest rate, estimated monthly payment, down payment requirements, closing costs, and whether mortgage insurance will apply.
It is also worth comparing offers from multiple lenders. A lower interest rate does not always mean the lowest overall borrowing cost, so review the fees and loan terms together.
4. Explore First-Time Home Buyer Programs in North Carolina
You may not need to save a traditional 20% down payment to purchase your first home. Depending on your eligibility and loan type, you may qualify for a lower-down-payment mortgage or a homebuyer assistance program.
For a first time home buyer in Charlotte, NC, exploring available assistance early can help you understand your options before you commit to a purchase price.
North Carolina down payment assistance
The North Carolina Housing Finance Agency offers programs that may help eligible buyers with down payments and other homebuying expenses.
Its published options include:
- NC Home Advantage Mortgage: Offers eligible buyers down payment assistance of up to 3% of the loan amount.
- NC 1st Home Advantage Down Payment: Offers eligible first-time buyers and military veterans up to $15,000 in down payment assistance, subject to program requirements.
Charlotte homebuyer assistance
The City of Charlotte also publishes information about its House Charlotte program, which provides assistance options for eligible buyers. Funding, income limits, purchase-price limits, and other requirements apply.
Important: Assistance programs can change, and not every buyer or property qualifies. Confirm current funding, eligibility, repayment or forgiveness conditions, and application deadlines directly with the program administrator and a participating lender.
5. Choose the Right Charlotte Neighborhood
The best neighborhood for you depends on your budget, lifestyle, commute, and future plans. Instead of trying to find the perfect area immediately, create a shortlist based on your priorities.
For example, a buyer who works in Uptown Charlotte may prioritize commute time and access to major roads. Someone who works remotely may care more about a home office, outdoor space, and nearby amenities.
As you compare areas, consider Charlotte and nearby communities such as Indian Trail, Matthews, Huntersville, Waxhaw, and Weddington. Each has its own housing options and local character. Do not assume that nearby communities will have the same prices, taxes, commute times, or amenities.
Create a home search checklist
Rank your priorities into three categories:
Must-haves
- A suitable number of bedrooms
- A manageable commute
- A monthly payment within budget
Nice-to-haves
- A larger yard
- A renovated kitchen
- A garage or extra storage
Deal-breakers
- Major structural concerns
- An impractical commute
- Monthly costs beyond your limit
This list can help you compare homes objectively instead of making a decision based only on appearance.
You can explore Charlotte real estate information and review available homes through the property search as you begin narrowing your options.
6. Work With a Real Estate Professional Who Understands Your Needs
A first-time buyer often has questions about pricing, offers, inspections, contingencies, and closing timelines. Having a real estate professional explain each stage can make the process easier to manage.
When choosing an agent, look for someone who listens to your priorities, understands the local market, communicates clearly, and helps you evaluate both the benefits and drawbacks of a property.
Mike Koman Realty can be a resource for buyers exploring homes in Charlotte and surrounding North Carolina communities.
Before choosing an agent, consider asking:
- How will you help me compare homes in my budget?
- What should I know about the neighborhoods I am considering?
- How will you help me evaluate a property’s asking price?
- What contingencies should I discuss before making an offer?
- How will you communicate important deadlines and next steps?
The goal is not simply to find a house. It is to make an informed decision that fits your finances and lifestyle.
7. Make a Competitive Offer Without Overstretching Your Budget
Once you find a suitable property, the next step is deciding whether to make an offer and what terms to propose.
Your offer may include the purchase price, proposed closing date, due diligence terms, financing terms, and other conditions. The right strategy depends on the property’s condition, recent comparable sales, seller priorities, and current market conditions.
Avoid assuming that every home requires an offer above asking price. Equally, do not assume that a property with a price reduction is automatically a bargain.
Before submitting an offer:
- Review recent comparable sales with your agent.
- Confirm your financing and cash requirements.
- Understand the due diligence fee and earnest money deposit.
- Discuss inspection and financing contingencies.
- Review the contract and its deadlines carefully.
In North Carolina, the due diligence fee and earnest money deposit are distinct. Their treatment depends on the contract terms and circumstances of the transaction. Ask your real estate professional or North Carolina real estate attorney to explain your obligations before signing.
A competitive offer should reflect what the property is worth to you and what you can comfortably afford, not just the fear of losing it.
8. Schedule Inspections and Review the Property Carefully
An accepted offer is an important milestone, but it is not the end of your research. A professional home inspection can identify concerns that may not be obvious during a showing. These can include roof deterioration, moisture intrusion, electrical issues, plumbing problems, or HVAC defects.
In Charlotte’s climate, it is especially useful to understand how well the heating and cooling system operates and whether there are signs of excess moisture or poor drainage.
Depending on the property, you may also want specialized inspections for pests, radon, septic systems, wells, or other concerns.
What should you do after the inspection?
- Read the report carefully.
- Ask the inspector to explain significant findings.
- Obtain estimates for major repairs when appropriate.
- Review your contractual options and deadlines with your agent or attorney.
- Decide whether to proceed, negotiate where appropriate, or use a contractual right to terminate.
An inspection is not a guarantee that a home will never have problems. It is a way to make a more informed decision before taking on the responsibilities of ownership.
9. Prepare for Closing Costs and the Final Walk-Through
Closing is the final stage before ownership transfers to you. During this phase, your lender, closing attorney, and other professionals coordinate documents, funds, and the transaction requirements.
Your closing costs may include lender fees, appraisal charges, title-related expenses, recording fees, prepaid insurance, property tax adjustments, and initial escrow deposits. The exact amount depends on your loan and transaction.
The Consumer Financial Protection Bureau explains that these expenses are separate from the down payment and may include both loan-related and other homebuying costs.
Before closing:
- Review your Closing Disclosure and compare it with your Loan Estimate.
- Confirm the amount you need to bring to closing.
- Arrange homeowners insurance.
- Verify wiring instructions independently with the closing attorney before sending money.
- Complete the final walk-through.
- Confirm that agreed-upon repairs and contract requirements have been addressed.
Your lender generally must provide the Closing Disclosure at least three business days before mortgage closing. Use that time to review the numbers and ask about anything you do not understand.
After the documents are signed and the transaction is completed, keep copies of your closing paperwork and set aside funds for future maintenance.
Conclusion
Buying your first home is easier to navigate when you understand the process before making major decisions. Start with a realistic budget, explore mortgage and assistance options, research Charlotte neighborhoods, and work with professionals who can explain your choices clearly.
As a first time home buyer in Charlotte, NC, you do not need to know every detail on day one. You need a clear plan, reliable information, and the confidence to ask questions before committing to a purchase.
Mike Koman Realty can help you explore Charlotte-area housing options and take the next steps toward finding a home that fits your goals. Begin by reviewing available properties, narrowing your preferred neighborhoods, and speaking with a lender about your financing options.
Frequently Asked Questions
How much money do I need to buy my first home in Charlotte, NC?
The amount depends on the home’s price, your mortgage program, your down payment, closing costs, and any assistance for which you qualify. Some mortgage programs allow lower down payments than others. Ask a lender to estimate your upfront cash needs before you start shopping.
Are there first-time home buyer grants in Charlotte, NC?
Eligible buyers may have access to state or local down payment assistance. Programs can have income limits, purchase-price caps, location requirements, and other conditions. Check current information from the North Carolina Housing Finance Agency and the City of Charlotte before relying on a specific assistance amount.
What credit score do I need to buy a home in North Carolina?
There is no single credit score requirement for every mortgage. Requirements depend on the loan program, lender, down payment, and your overall financial profile. Speak with lenders about the options available to you and whether improving your credit could help.
What is the first step for a first-time home buyer in Charlotte?
Start by reviewing your finances and setting a comfortable monthly housing budget. Then speak with a mortgage lender about preapproval and available loan programs. Once you understand your budget, you can search for homes and neighborhoods that match your needs.
Also Read: How to Buy a House in North Carolina